Banks pay the bill for last year's failures

America's biggest banks are paying the last of the bill for the regional banking panics of early 2023. Under Federal Deposit Insurance Corporation (FDIC) rules, the multibillion-dollar cost of protecting uninsured depositors at Silicon Valley Bank and Signature Bank has to be recouped through a special assessment on the industry. Wall Street's largest lenders are paying most of it.
Why there is a bill at all
Deposit insurance in America covers $250,000 per depositor per bank. Most of the money at Silicon Valley Bank and Signature Bank sat in accounts well above that limit, belonging to technology start-ups, venture funds and crypto firms. When the two banks failed in March, regulators invoked the systemic risk exception in federal law, which allowed the FDIC to protect every depositor in full to stop the run spreading. The same law says that any loss to the Deposit Insurance Fund from using that exception must be recovered from the banking industry, not from taxpayers.
The FDIC finalised its rule in November. It estimated the cost of covering uninsured depositors at about $16.3 billion and set the assessment at an annual rate of about 13.4 basis points on each bank's uninsured deposits, excluding the first $5 billion, collected over eight quarters starting this year. The exclusion means that small and mid-sized banks pay nothing, and the burden falls on those with large pools of uninsured deposits, which in practice means the biggest banks.
A charge on fourth-quarter profits
JPMorgan Chase took a $2.9 billion charge in its fourth-quarter results, and Bank of America, Wells Fargo and Citigroup each took hits of more than $1 billion. The assessment is in effect a tax on banking earnings that nobody could hedge, and it takes capital that might otherwise have gone on share buybacks or new lending. Stability has a price, and the invoice arrives after the event.
Accounting rules explain why the hit came all at once. Although the cash is paid over two years, banks must record an expense when it is probable and can be estimated, so the largest lenders booked the whole amount in the final quarter of 2023. Earnings for the quarter looked worse than the underlying business, and several banks presented adjusted figures excluding the charge.
Rough justice for the giants
There is a case that the biggest banks are paying for a crisis they profited from. During the panic in March, depositors moved billions of dollars from regional lenders to the largest institutions, which they regarded as too big to fail. JPMorgan then bought First Republic in May in a deal arranged by the FDIC, and went on to report a record annual profit. Charging the banks that gained deposits during the run for the cost of stopping it has a certain logic.
The assessment also exposes the implicit guarantee behind uninsured deposits. By protecting every depositor at two mid-sized banks, regulators signalled that large depositors elsewhere would probably be protected too. The special assessment prices that guarantee after the fact, and the price falls mainly on institutions that were never in trouble.
Precedent from 2009
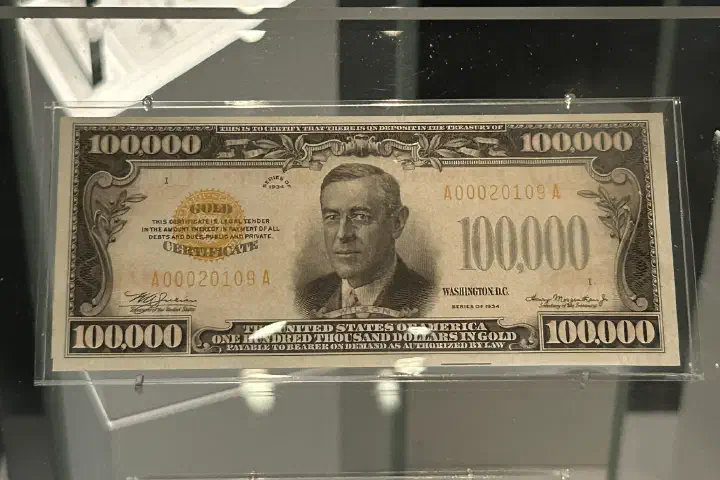
The FDIC has done this before. In 2009, with bank failures draining the insurance fund, it imposed a special assessment on the industry and then required banks to prepay three years of regular premiums at the end of that year. The savings-and-loan crisis of the late 1980s showed the alternative: the insurance fund for thrifts ran out of money, and taxpayers bore most of the clean-up cost. Since then, Congress and regulators have tried to make sure that the industry, not the public, pays for deposit insurance.
Winners and losers
Shareholders of the largest banks are the clearest losers, though the damage is limited. For JPMorgan the charge is a small fraction of annual profits, and the payments are spread over two years. Community and regional banks below the threshold escape the levy, which slightly improves their competitive position. Depositors with large balances gain, since the episode confirmed that regulators will protect them in a crisis at a cost borne by others.
The levy also arrives alongside higher regular premiums. The FDIC raised its standard assessment rates for all banks from the start of 2023 to rebuild the insurance fund towards its statutory target, and the special assessment comes on top. Banks pass part of these costs to customers through lower deposit rates and higher fees, so savers bear some of the bill indirectly.
The case against the column
The strongest counterargument is that the charge is a one-off and too small to change the big banks' capital plans. Their capital ratios are well above minimum requirements, their profits are high, and the cost is already booked. Investors may simply look through it, as they did through the adjusted figures in the results.
That is largely right on its own, but the levy does not come alone. Regulators published a proposal in July to raise capital requirements for large banks under the final stage of the Basel III rules, and a separate proposal would require more long-term debt. With higher capital requirements on the way and the levy taking cash each quarter, bank boards have reasons to be cautious about returning capital. The FDIC has also warned that the estimated losses may change as the failed banks' assets are sold, which could extend the collection period.
What to watch
The first signs will come in the banks' capital plans and their buyback announcements over the coming quarters. The final version of the Basel rules, and whether regulators soften it after heavy criticism from the industry, will matter more than the levy for buybacks. Updates from the FDIC on the eventual loss from the failures will show whether the bill grows.
The FDIC levy makes the banking system collectively liable for its weakest members. The strongest balance sheets have paid for the failures of 2023, and their shareholders will probably see it in smaller buybacks this year. The effect will fade by the end of next year as the payments run off, but by then the capital rules will have taken over as the main constraint on returns to shareholders.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.