DeepSeek's shock sends investors running to bonds
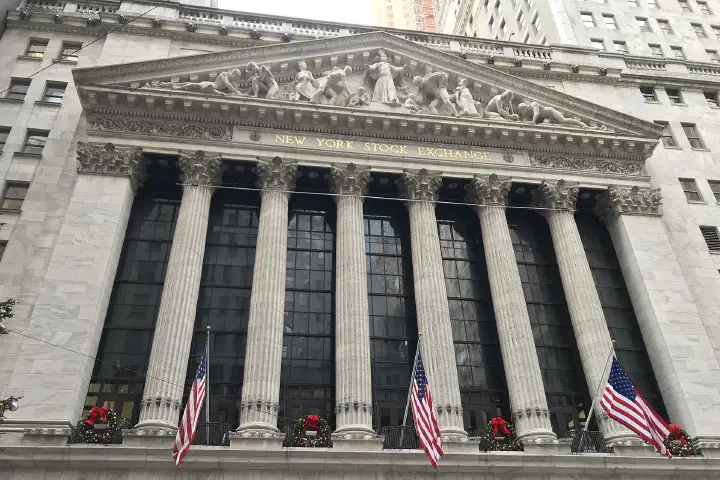
Nvidia lost $589 billion of market value on 27 January, the largest one-day fall for any company in history. The cause was a start-up in Hangzhou. DeepSeek released an open-weights model that reasons about as well as the best American systems, and was trained, by its account, for a tiny fraction of what Western labs spend.
A week of warnings ignored
The shock took a week to land. DeepSeek, which is backed by the Chinese quantitative hedge fund High-Flyer, published its V3 model in late December with a technical report claiming that the final training run cost less than $6 million, using Nvidia H800 chips designed to comply with American export rules. Its R1 reasoning model followed on January 20th. Markets paid little attention until the company’s chatbot app climbed to the top of Apple’s App Store download charts in America over the weekend, and Monday’s open turned a technical debate into a selling panic.
Export controls explain why the efficiency matters so much. Washington has tightened its restrictions on chip sales to China repeatedly since October 2022, on the theory that denying Chinese labs the best hardware would keep them a generation behind. The H800 was itself caught by the tightening of October 2023, months after it went on sale. If a lab working with restricted hardware can reach the frontier, the policy of limiting compute looks weaker, and so does the assumption behind the highest chip valuations that scarcity will last.
Do the chips still matter?
The AI boom rested on the belief that performance scales with compute, and that only vast proprietary clusters could deliver it. If clever algorithms and distillation can match frontier models with far fewer high-end chips, the hundreds of billions of dollars companies plan to spend on GPUs look harder to justify. Hyperscalers’ capex plans assumed hardware would stay scarce. They now face the risk that efficiency gains push prices down.
The spending plans are on the record. Microsoft has said it expects to spend about $80 billion on AI-capable data centres in its current fiscal year, Meta has guided to between $60 billion and $65 billion of capital spending this year, and last week OpenAI, SoftBank and Oracle announced the Stargate venture with a pledge of up to $500 billion. Every one of those numbers assumes that the price of useful intelligence will be set by scarce, expensive chips. A cheaper route to similar models would shift the returns from chip suppliers towards the companies that use the models.
Into Treasuries
As crowded tech positions unwound, investors ran for government bonds. US Treasury yields fell sharply as bond desks priced out some inflation risk and bought duration, treating the breakthrough as a productivity shock that would bring prices down. The Nasdaq Composite fell about 3 per cent on the day, while the yen and the Swiss franc gained, the usual pattern when investors cut risk in a hurry.
The bond market reaction has two parts. The first is a flight to safety, as funds that had borrowed against concentrated tech holdings raised cash and parked it in the most liquid asset available. The second is a change in expectations: if AI becomes cheap faster, the investment boom that has supported American growth may cool, and cheaper computing may lower costs across the economy. Both lower the term premium, and both give the Federal Reserve, which meets this week, a little more room to cut later in the year.
Winners and losers
The heaviest losers were the companies whose valuations depended on the capex boom continuing unchanged: Nvidia and other chip designers, makers of networking equipment, and the power producers that had rallied on expectations of vast data-centre electricity demand. The winners are less obvious but real. Software companies and businesses that buy AI services stand to pay less for them, and open-weights models weaken the pricing power of closed American labs. Bondholders collected a windfall from the rally in duration.
The losses were concentrated but large enough to matter for the whole market. The biggest American technology companies make up a larger share of the S&P 500 than any group of stocks has in decades, so a sell-off in AI names moves index funds, pension portfolios and the household wealth that has supported consumer spending. That concentration is the channel through which a model released in Hangzhou can reach the American economy.
The precedent of fibre
The closest historical parallel is the telecoms boom of the late 1990s. Carriers laid far more fibre-optic cable than demand required, on the assumption that bandwidth would stay scarce, and improvements in transmission technology multiplied the capacity of every strand already in the ground. Prices collapsed, many carriers failed, and the users of cheap bandwidth prospered in the following decade. The parallel is imperfect, since the hyperscalers are far more profitable than the carriers were, but it shows who tends to capture the gains when a scarce input becomes plentiful.
The case for the chipmakers
The strongest counterargument is that cheaper models raise total demand for compute rather than reducing it. If the cost of running a capable model falls, companies will deploy AI in many more products, and inference, rather than training, will absorb the chips. DeepSeek’s cost claim also covers only one training run, not the research, failed experiments and hardware that preceded it. Those points may well prove right over several years, but they do not rescue valuations that assumed both rising volumes and today’s margins.
What to watch
The next signals are the hyperscalers’ quarterly results over the next two weeks, where investors will look for any trim to capex guidance, and Nvidia’s own results next month. DeepSeek has shown that spending the most on chips does not guarantee a lasting lead. Investors will probably keep marking down chipmakers and heavy AI spenders until the hyperscalers prove their capex still pays, and ten-year Treasury yields should hold below their January peak while that doubt persists.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.