Diwali: India's gold habit is weighing on the rupee
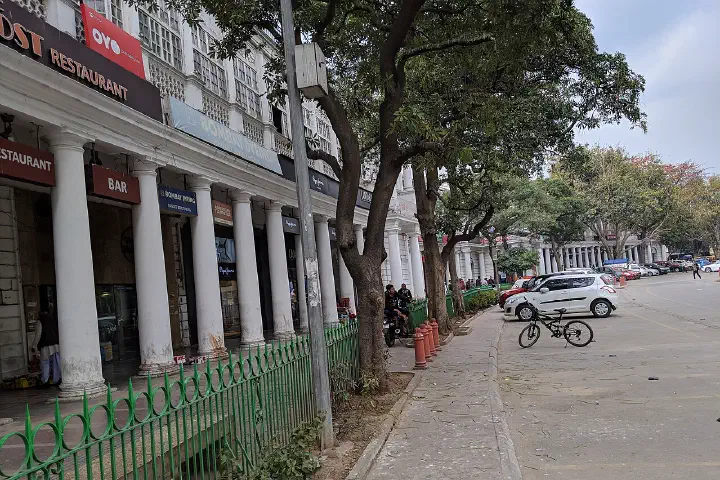
The rupee has fallen past 83 to the dollar for the first time, and India's households are about to buy a great deal of gold. As millions celebrate Diwali on 24 October, shopping districts in Mumbai and New Delhi are seeing the usual festive rush for jewellery and coins. Buying gold at Dhanteras and Diwali is among the oldest consumer traditions in the world, and a sign of prosperity at home. On Mumbai's currency desks it is dreaded. India's appetite for bullion is a steady, unhedged drain on the current account, and it has helped push the rupee through that sensitive threshold.
India imports almost all the gold it consumes, which makes bullion the second-largest item on its import bill after crude oil. In a normal year foreign portfolio inflows and strong software exports pay for it comfortably. In 2022 the festive season has arrived when India is badly exposed abroad. With the Federal Reserve driving global rates higher and crude oil above $90 a barrel, India's terms of trade have worsened sharply, leaving the rupee at the mercy of household buying habits.
A deficit already widening
The external accounts were weakening well before the festival. The current-account deficit reached 2.8 per cent of GDP in the April-to-June quarter, the first of the fiscal year, as the oil bill soared, and foreign portfolio investors have been net sellers of Indian shares for much of the year as American yields rose. A country that needs foreign capital to cover a widening deficit is poorly placed when that capital is heading home to earn more in dollars.
From bazaar to dealing room
The link from the jewellery bazaar to the currency market is direct. When Indian shoppers buy coins, bangles and bars, bullion dealers must pay for the imports in US dollars. In a festive season when imports can reach eighty to one hundred tonnes in a single month, that means an immediate outflow of five to six billion dollars.
Gold is an imported consumer asset that adds nothing to the country's productive capacity, so the festive outflows are a straight leak. The money builds no infrastructure and no export industry. It turns rupee savings into metal that sits in vaults and safety deposit boxes. With the trade deficit already near thirty billion dollars a month, a record, an extra gold bill of several billion forces the Reserve Bank of India to choose between spending its reserves and letting the rupee fall.
Mumbai's expensive defence
The Reserve Bank of India has put up a stout defence through 2022, running its foreign exchange reserves down by nearly one hundred billion dollars from their peak to smooth the currency's moves. That peak, of more than $640 billion, came in September 2021. Defending a currency against steady import demand is costly and ends up defeating itself. The central bank's dollar sales drain rupees from the banking system, tightening financial conditions and raising borrowing costs just as festival spending calls for credit.
Interest rates are doing some of the work as well. The RBI has raised its repo rate four times since May, most recently by half a point on 30 September to 5.9 per cent, and consumer price inflation, at 7.41 per cent in September, has now stayed above the 6 per cent ceiling of its target band for nine months running. Three straight quarters outside the band oblige the central bank, under its own law, to explain the failure in writing to the government. A weaker rupee raises the price of imported fuel and edible oil, which feeds straight back into that inflation.
The government tried to curb demand earlier this year by raising the basic customs duty on gold imports to 12.5 per cent. Decades of experience show that tariffs do not kill India's taste for gold. They widen the local premium and encourage smuggling, and the pressure on the currency stays where it was. For a typical Indian household, facing high inflation and choppy share prices, physical gold is still the store of value it trusts most.
Attempts to turn that habit into paper have had modest success. Since 2015 the government has sold sovereign gold bonds, which track the metal's price and pay a small interest rate, and has run a gold monetisation scheme meant to draw household jewellery into bank deposits. Neither has displaced the demand for coins and ornaments that can be worn, gifted at weddings and passed down without paperwork.
The lesson of 2013
India has been here before. In 2013 the current-account deficit reached a record 4.8 per cent of GDP in the fiscal year to March, gold imports were blamed for much of it, and the rupee plunged to record lows during the summer's taper tantrum. The government raised gold import duty in stages and imposed rules tying bullion imports to re-exports, and the RBI under its new governor, Raghuram Rajan, drew in more than $30 billion of deposits from Indians abroad through a subsidised swap scheme. The rupee stabilised, but only once the deficit had been squeezed and foreign capital returned.
Who gains from a weak rupee
Some benefit. India's software exporters earn in dollars and pay most of their costs in rupees, so every step down in the currency widens their margins. Families receiving remittances from the Gulf, America and Britain get more rupees for each dollar sent home. The losers are importers of fuel and fertiliser, companies with unhedged dollar debt and the government, which subsidises cooking gas and fertiliser and pays more for both as the currency falls.
The strongest objection is that the rupee has held up better than the yen or the pound this year, and that the festive gold bill is seasonal, fading after the wedding season in the new year. That is fair, and the reserves remain large. The seasonal bill arrives, however, on top of a structural oil deficit and portfolio outflows that are not seasonal, and every dollar spent on bullion is one fewer dollar in the RBI's war chest. The October trade figures, due in mid-November, and the central bank's December policy meeting will show how much the festival cost.
The irony of Diwali 2022 is that a celebration of wealth at home is eroding the purchasing power of the national currency. While Indian savers keep putting their wealth into imported bullion, the rupee will take the hit from every rise in oil prices or US rates, and this winter it will probably weaken further. The festival lights will shine across India tonight, but in the central bank's dealing rooms the gold bill promises a long, cold winter for the rupee, with importers and the government's subsidy budget paying the most for it.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.