Is Japan about to loosen its grip on bonds?
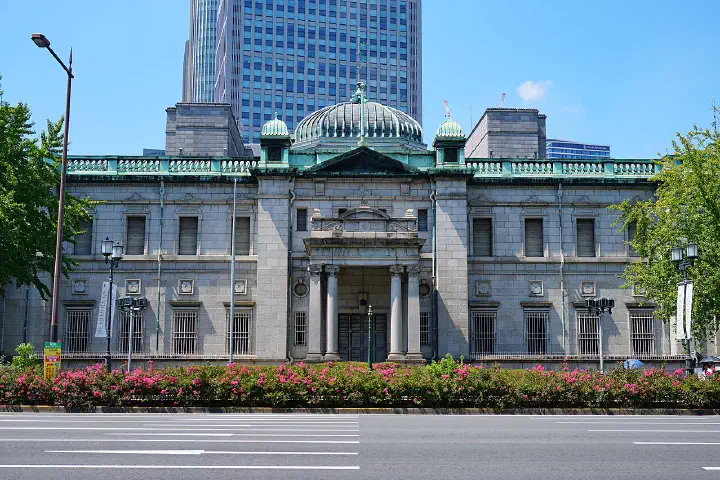
The yen sits near 139 to the dollar and headline inflation is comfortably above target, and speculation is growing that Kazuo Ueda will loosen or scrap the Bank of Japan's yield curve control (YCC). The BoJ is the last big central bank still holding rates down, and its hold on the government bond market is getting harder to sustain. Keeping a ceiling on ten-year JGB yields is costing it an ever larger balance sheet.
Seven years of pegging
Yield curve control began in September 2016, when the BoJ, already charging banks a negative rate of 0.1 per cent on some reserves, added a target of around zero for the ten-year yield. The aim was to keep borrowing costs low across the curve without the open-ended bond buying of the earlier quantitative easing programme. For several years it worked cheaply, because inflation stayed low and few investors wanted to test the Bank. The band around the target was widened modestly in 2018 and 2021 with little fuss.
The pressure came with global inflation. As other central banks raised rates last year, the gap between Japanese and foreign yields widened, the yen slid past 150 to the dollar in October, and the Ministry of Finance intervened to support it for the first time since 1998. In December, under Ueda's predecessor Haruhiko Kuroda, the BoJ surprised markets by widening the band to 0.5 per cent either side of zero. Ueda took over in April and has so far kept the framework intact while promising a review of past policy.
Defending the cap
To defend the 0.5 per cent cap, the BoJ has had to buy huge chunks of the JGB market. Trading in the secondary market has dried up and the yield curve is bent out of shape. Widening the band, or moving the target to shorter maturities, would let the market set prices again. The risks spill well beyond Japan. Higher yields at home could tempt Japanese investors to bring large sums back from abroad, draining money from US Treasuries and European government bonds.
The BoJ now owns more than half of all outstanding government bonds, a share that has kept climbing as it absorbs whatever the market wants to sell at the capped yield. That has perverse effects. Some individual bonds have become so scarce that they barely trade, so the yields that are supposed to guide the economy reflect the Bank's purchases rather than any assessment of risk. Banks and insurers that need to hedge interest-rate exposure find the market too thin to do so efficiently.
Why the case for change is building
Japan's core inflation, excluding fresh food, has been above the BoJ's 2 per cent target since the spring of last year. Wages are finally moving too: this year's spring negotiations between unions and large employers produced the biggest pay rises in about three decades. That is the combination the BoJ has spent years waiting for. If inflation is to settle around 2 per cent on the back of rising pay, holding long-term yields near zero looks increasingly hard to justify.
A weak yen adds pressure. Import prices for fuel and food squeeze households, and a central bank that caps yields while others raise them keeps the currency under strain. The obvious options are to widen the band again, raise the cap outright, shorten the targeted maturity to five years or less, or drop the long-end target entirely while keeping short rates negative.
Exits rarely go smoothly
Precedent suggests that leaving a market peg is messy. In November 2021 the Reserve Bank of Australia abandoned its target for three-year government bond yields after investors pushed yields well above it, and the Bank later acknowledged that the exit had been disorderly and damaged its reputation. In January 2015 the Swiss National Bank dropped its cap on the franc without warning, and the currency jumped violently within minutes. Both cases taught the same lesson: a central bank that signals an exit invites speculators to front-run it, while one that surprises the market takes the shock in a single day.
The BoJ has chosen surprise before, most recently in December. That makes each policy meeting a potential event, including the one at the end of this month, and keeps volatility in the JGB market higher than the cap alone would imply.
The trail back to Treasuries
Japan is the largest foreign holder of US government debt, with more than $1trn in Treasuries, and its life insurers and pension funds hold large amounts of European and Australian bonds too. They bought those assets because domestic bonds yielded almost nothing. With American short-term rates now far above Japan's, the cost of hedging dollar bonds back into yen has become punishing, eating most or all of the extra yield. Higher JGB yields would give these institutions a reason to rebalance towards home.
The flows would not happen overnight. Insurers match long-dated liabilities and move slowly, and they are more likely to direct new money into JGBs than to dump existing foreign holdings. But at the margin, a regular buyer of Treasuries and European bonds would be buying less, at a time when the American government is issuing heavily. Carry traders who borrow in yen to buy higher-yielding assets elsewhere would also face higher funding costs and a stronger yen.
The case for waiting
The strongest argument against a near-term change comes from Ueda himself, who has repeatedly stressed that the BoJ wants to be sure inflation is sustained by wages rather than import costs. Much of Japan's current inflation still reflects energy and a weak currency, and some of it may fade. A premature exit that then had to be reversed would damage the Bank's credibility far more than keeping the cap a little longer.
That argues about timing rather than direction. The distortions in the bond market grow each month the cap stays in place, and the longer the Bank waits, the bigger the eventual repricing. Japan's bond market needs YCC gone, but letting domestic yields rise will jolt global bond portfolios that have grown used to cheap yen funding, and Treasuries would probably feel it first. The likeliest path is a further loosening of the band within months rather than years, with long-dated Treasury yields pushed up and the yen firmer as Japanese money starts to come home.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.