Japan wants pay rises before rate rises
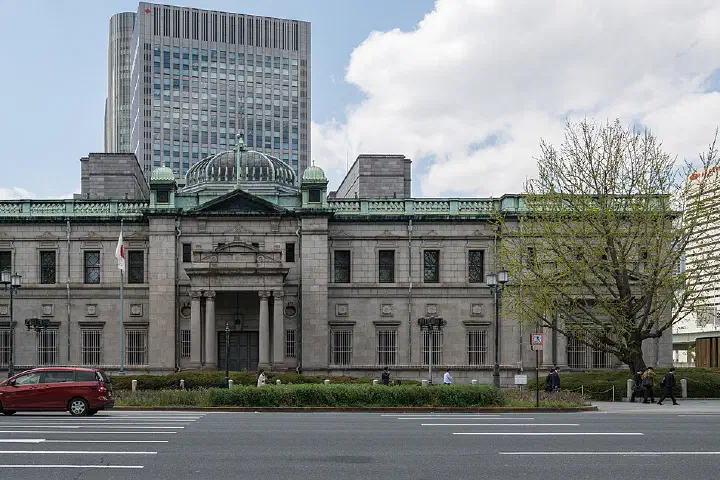
The Bank of Japan kept its benchmark rate at minus 0.1 per cent in January, disappointing traders who had bet on an immediate end to negative rates. Governor Kazuo Ueda made plain that the decision depends on the spring 'Shunto', the annual wage negotiations between big companies and trade unions.
Eight years below zero
Japan has had a negative policy rate since January 2016, when the BoJ under Haruhiko Kuroda cut its rate on some reserves below zero. Later that year it added yield curve control, pinning the ten-year government bond yield near zero. The aim was to break a deflationary mindset that had lasted since the 1990s. For years the policy produced little inflation, and the BoJ became the last major central bank still running negative rates.
That changed after 2021. Import prices surged as energy costs rose and the yen weakened, and Japan's core consumer price inflation has exceeded the BoJ's 2 per cent target since the spring of 2022. Ueda, who took over in April 2023, has already loosened the yield-curve cap in stages, first allowing the ten-year yield to rise to 1 per cent and then treating that level only as a reference point. Ending negative rates is the next step, and markets had hoped it would come this month.
Waiting for the wage round
Japanese wages barely grew for three decades, and that stagnation kept deflationary expectations anchored across the economy. The BoJ will not unwind its stimulus until it has solid evidence that pay rises will top four per cent, enough to sustain a healthy cycle of rising wages and prices. Big Japanese companies are reporting record profits. Until those profits turn into permanently higher base pay, the BoJ will stay on hold.

Last year's round offered encouragement. The Rengo trade union federation reported an average pay rise of about 3.6 per cent, the highest in three decades, and it has set a goal of at least 5 per cent this spring. Several large companies have already signalled generous offers. The weakness is further down the chain: most Japanese workers are employed by small and medium-sized firms, which have less pricing power and thinner margins, and whose pay settlements come later and tend to be smaller.
Why inflation alone is not enough
The BoJ's reasoning is that inflation driven by import costs will fade on its own. If wages do not follow, households will cut spending as their real incomes fall, and prices will slip back once energy and currency effects wash out. Real wages in Japan have fallen for well over a year, because pay has lagged behind prices. A rate rise into that weakness would risk choking off demand before a self-sustaining cycle has taken hold.
The earthquake on the Noto peninsula on New Year's Day added a further reason for caution. Its economic effect is likely to be limited and local, but it gave the BoJ another reason to avoid surprising markets this month.
The memory of 2000 and 2006
The BoJ's caution has a history. In August 2000 it ended its zero-rate policy despite objections from the government, only to reverse course early the next year as the economy slumped and to begin quantitative easing. It tried again in 2006, ending that programme and raising rates twice, before the global financial crisis pulled Japan back into deflation. Both episodes are widely seen in Tokyo as premature exits, and Ueda, who sat on the BoJ's board in 2000 and voted against ending zero rates, knows them intimately.
Winners and losers from a move
An end to negative rates would help Japanese banks, whose lending margins have been squeezed for years, and savers, who have earned almost nothing on deposits. Life insurers and pension funds, which have struggled to earn adequate returns on domestic bonds, would gain from higher yields on new purchases. It would raise the government's borrowing costs over time, a sensitive matter for a state whose debt exceeds twice the size of its economy. Exporters that have enjoyed the weak yen, which traded past 150 to the dollar in November, would lose some of that advantage if the currency strengthened.
The global effects could be larger. Japanese investors hold large amounts of foreign bonds, and higher yields at home could draw some of that money back. Investors who borrow in yen to buy higher-yielding assets abroad would face higher costs and currency losses if the yen rose.
The case for moving sooner
The strongest counterargument is that the BoJ risks falling behind. Inflation has been above target for nearly two years, and waiting for proof of wage growth means acting only after the evidence is overwhelming. A weak yen feeds imported inflation, and delay could leave the BoJ moving just as other central banks begin to cut, magnifying swings in the currency. A small rise from minus 0.1 per cent to zero would still leave policy very loose.
That argument has merit, but it underestimates how costly a failed exit would be for the BoJ's credibility. Having reversed course twice before, the bank would rather move a few months late than have to retreat again. A single meeting's delay costs little if the wage evidence then arrives.
What to watch
The first tally of the Shunto, usually published by Rengo in mid-March, is the key data point. The BoJ meets again in March and April, and it will also watch its own regional survey of business conditions and wage plans. Services inflation, which reflects domestic labour costs more than imported goods, will show whether price rises are becoming self-sustaining. The yen matters too: the finance ministry intervened to support the currency in the autumn of 2022, and a renewed slide would add pressure on the BoJ to act.
Ueda will not move on a burst of inflation alone. If the Shunto delivers pay rises above four per cent, the BoJ will probably end negative rates soon afterwards. If it disappoints, the wait goes on. The most likely outcome is a strong first tally in March and a first rate rise in March or April, followed by a long pause rather than a series of hikes.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.