Prime Day: Four days of discounts, and tariffs

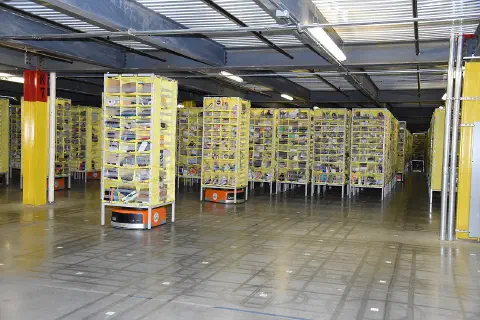
Amazon stretched Prime Day to four days this year and filled it with millions of promotions. The event also became the place where steep online discounting ran into the rising cost of import tariffs, and the tariffs looked like winning.
From two days to four
Prime Day began in 2015 as a one-day sale to mark Amazon's twentieth birthday and settled into a two-day summer fixture. Doubling it this year gave the company more room to show volume at a time when shoppers are counting pennies. It also gave sellers more days in which to shift stock they would rather not hold into the autumn. A longer sale is a convenient way to spread thin margins over more units, which is not the same as widening them.
Big discounts, thin margins
Third-party sellers and mass-market brands advertised eye-catching discounts to keep inflation-weary shoppers buying. The arithmetic behind the offers was poor. Since early spring merchants have paid baseline tariffs of 10 to 30 per cent on imported electronics, home furnishings and clothing. Many cleared stock at margins that were razor-thin or negative, largely to raise the cash needed to service the debt that funds their working capital.
Independent sellers account for most of the units sold on Amazon, and a large share of them source goods from China. Those goods faced a tariff of 145 per cent for several weeks in April and May before the Geneva truce cut it to 30 per cent. A seller who paused orders during that spell, then restocked at the lower rate, is still paying far more at the border than a year ago. Amazon's own fees for storage, fulfilment and advertising do not fall because the seller's landed cost has risen.
Stock bought before the tariffs
Much of what was on sale arrived before the duties bit. American imports surged in the first quarter as firms raced to beat the April announcements, enough to push measured GDP into a small contraction. That inventory carries the old, lower cost, and it can be discounted without much pain. The goods ordered since April cannot. Once the pre-tariff stock is gone, the discount a seller can afford shrinks by roughly the size of the duty.
Prices have further to go
A big platform can conjure demand for a few days by holding prices down. It cannot keep doing so when the goods cost more to bring into the country. The four-day sale looked a good deal like a final clearance of stock bought before the tariffs, plus whatever discounted lines sellers needed to shift.
The 2018 tariffs on washing machines offer a guide to what follows. Retail prices of washers rose after the duties took effect, and so did prices of dryers, which were not tariffed but are usually bought in pairs. Sellers used the cover of a tariff to reprice whole categories. Walmart warned in May that it would have to raise some prices because of tariffs, and Amazon's sellers have less pricing power than Walmart does.
What the bond market is watching
For fixed-income investors the question is whether a one-off rise in the price level turns into lasting inflation. Economists generally treat a tariff as a single shift in prices that a central bank can look through, provided expectations stay anchored. The danger lies in a series of increases arriving months apart, which can produce a run of high monthly readings that households and firms start to treat as normal. Short-dated Treasury yields will move on which of those readings the Fed chooses to believe.
There is also a credit angle. Sellers that fund inventory with short-term borrowing pay interest on the goods and on the duty while the stock sits in a warehouse. With policy rates where they are, that carrying cost is higher than at any point in the previous decade, which is one reason so many chose to discount now rather than wait for autumn demand.
Who gains and who loses
Amazon itself is the least exposed party. It earns commissions and fees on each sale whatever the seller's margin, and a busier event means more of both. Big brands with loyal customers can pass costs on and still move volume. The losers are small importers financed by short-term credit, for whom a discount that does not cover the duty is a way of converting inventory into cash at a loss, and the lower-income households that spend more of their budgets on the goods most exposed to tariffs.
The case against
The counterargument is that consumer inflation has stayed moderate so far this year, and that competition between sellers may keep prices down longer than the tariff arithmetic implies. There is something in that. Some foreign suppliers will cut their prices to keep American shelf space, and some importers will find cheaper sources in Vietnam, India or Mexico. Neither adjustment is quick, and neither is complete, because tariffs have been raised on nearly every source at once. Moving production means finding new factories, qualifying new suppliers and rebuilding supply chains, which takes seasons rather than weeks, and the new source often carries a tariff of its own.
The Federal Reserve, which has held its policy rate at 4.25 to 4.5 per cent all year, has said it expects tariffs to push goods prices up over the summer, and it meets again at the end of July. The monthly consumer price figures for core goods are the ones to watch. A clear rise in those prices would confirm that the discounting phase is over. A flat reading through the autumn would suggest that foreign suppliers and sellers' margins are absorbing more than expected.
Prime Day was an impressive piece of salesmanship, but once the discounts lapse sellers will probably have to lift shelf prices for good, and shoppers will pay the border taxes that this sale briefly hid. Expect the evidence to show up in core goods prices over the next few months, and expect the back-to-school and holiday promotions to be noticeably less generous than this one.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.