Retailers ordered for a boom that never came
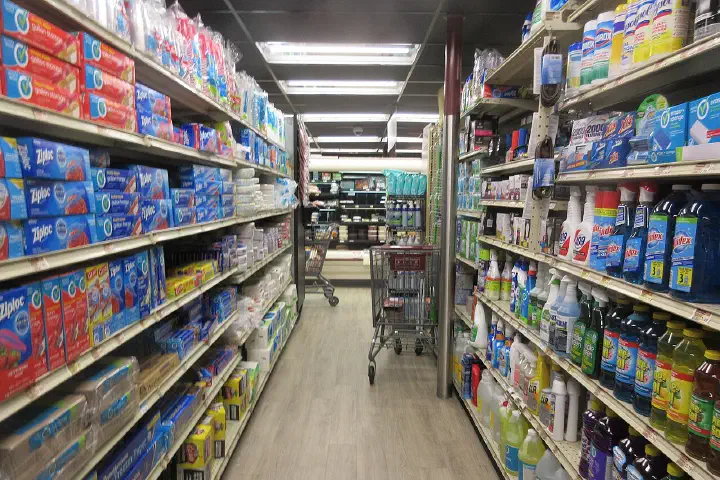
Target's operating margin fell to 3.9 per cent in the third quarter, from 8.6 per cent a year earlier, as the company cut prices hard to empty its warehouses. It was the clearest sign of a bad earnings season for America's big retailers. After two years of boasting about their supply chains and record demand, the largest mass merchants have had to admit that their distribution centres are stuffed with hundreds of millions of dollars of goods nobody wants. They placed huge orders for a pandemic spending boom that had already ended.
It is the bullwhip effect in textbook form. In 2021 shipping lanes were clogged, freight rates were soaring and demand for home goods, casual clothes and patio furniture was red hot. Procurement managers panicked. Afraid that empty shelves would cost them market share over the holidays, retailers began ordering two or three times what they needed, twelve to eighteen months ahead. By the time the containers had cleared West Coast ports and reached regional distribution centres in mid-2022, American shoppers had moved on.
Three warnings in one year
Target has been saying this in instalments. In May its first-quarter results showed margins crushed by excess stock and freight costs, and the shares suffered their worst day since the 1987 crash. In June it warned again, saying it would cancel orders and cut prices to clear inventory. This month it reported the third-quarter squeeze, cut its forecast for the holiday quarter to a fall in comparable sales, and announced a plan to take $2bn to $3bn of costs out of the business over three years. The shares lost more than a tenth of their value on the day.
Not every retailer is in the same position. Walmart, which reported a day earlier, said it had made progress in cutting excess inventory and raised its full-year outlook, helped by grocery sales to shoppers trading down from pricier chains. The difference is mix: a retailer that sells mostly food and household basics can recover faster than one that leans on discretionary goods such as home furnishings and electronics.
Shoppers switched to services
The speed of the shift caught merchandisers off guard. As restrictions lifted and travel resumed, household budgets swung away from physical goods towards experiences such as flights, hotels and restaurants. At the same time, inflation at a four-decade high in groceries, petrol and utilities was eating a growing share of disposable income, leaving middle-class shoppers with little spare cash for new televisions, small kitchen appliances or clothes.
Distribution centres ended up full of the wrong stock at the wrong time. Bulky, expensive discretionary items sat on pallets, taking up space and running up storage, insurance and handling charges. A garment that sells for fifty dollars in spring loses value every week it sits in a warehouse, as fashions change and the season passes. For retail treasurers the glut was a drain on working capital they could not afford to leave running.
How the whip cracks
The mechanism was described by Jay Forrester at the Massachusetts Institute of Technology more than sixty years ago, and later named by managers at Procter & Gamble who noticed wild swings in orders for nappies whose actual use was steady. Each link in a supply chain adds a safety margin to the order it passes upstream. When lead times lengthen, the margins grow, so a modest rise in shop-floor demand becomes a large rise in orders at the factory.
The reverse is just as sharp. When demand cools and lead times shorten, every link tries to shed its safety stock at once, and orders collapse by more than sales do. Container freight rates have already fallen by more than half from their peak, which makes each retailer less willing to hold spare stock and deepens the cut in orders.
Markdowns eat the margin
To stop the bleeding, the big retailers started discounting heavily. Surplus patio furniture, electronics and seasonal clothing were marked down by thirty, forty and fifty per cent. The markdowns moved volume and freed up space, but they did great damage to gross margins. Every dollar of stock written down or sold below wholesale cost came straight off quarterly operating income. Target also blamed rising theft, which retailers call shrink, for part of the damage.
The damage is now travelling back up the global supply chain. Having cleared their surplus at a loss, the big retailers have abruptly cancelled factory orders for next spring and summer. Manufacturing centres in Vietnam, Bangladesh and southern China are seeing export orders drop suddenly, and factories there are closing and laying workers off. China's exports fell year on year in October for the first time since the early months of the pandemic.
Who gains from the glut
Shoppers are the obvious winners, and so are off-price chains, which buy other retailers' unwanted stock at a fraction of its cost and sell it at a discount that still leaves them a margin. The losers are the manufacturers and freight companies upstream, and the retailers whose shares were priced for the margins of 2021.
The case against gloom is that the worst of the markdowns may already be behind the sector. Retailers that have cleared their shelves before the holidays can enter next year with leaner stock, lower freight costs and fewer promotions, which would let margins recover quickly. That is plausible for the best-run chains. It depends, however, on shoppers spending steadily through the holidays, and the fourth-quarter results due in the new year will show whether that happened.
The inventory glut of 2022 marks the turning point for goods inflation. By cutting prices to unload their pandemic ordering mistakes, the big retailers have started a spell of falling goods prices that should show up in the inflation data over the coming months, with shoppers collecting the bargains and shareholders paying for them. The markdowns will help the headline inflation figures, but retail share prices have taken damage that will need years of careful management to repair, and suppliers in Asia will feel the cancelled orders well into the first half of next year.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.