Rising costs threaten company profits
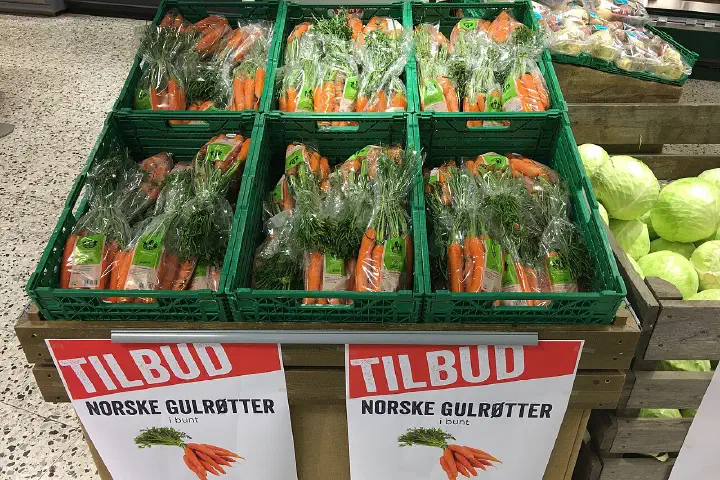
The producer price index rose 0.4 per cent in August from July, and core wholesale prices rose 0.2 per cent. Input costs are climbing through the industrial supply chain, and companies' profit margins look increasingly exposed.
Costs build up upstream
Producer prices capture inflation before it reaches the shops. Right now they are being pushed up by dearer diesel for haulage, 50 per cent steel tariffs on finished machinery and high prices for chemical feedstocks, and all three are showing up on company income statements. For manufacturers, chemical makers and food distributors, the cost of goods sold is rising much faster than revenue.
The gap between the headline and core readings tells its own story. Core producer prices exclude food and energy, so a headline rise twice the size of the core rise points to fuel and feedstocks as the main source of pressure. Energy costs move through the chain in stages: diesel raises freight bills at once, feedstock costs reach chemical and plastics makers within weeks, and both arrive in the price of packaged and manufactured goods over the following months.
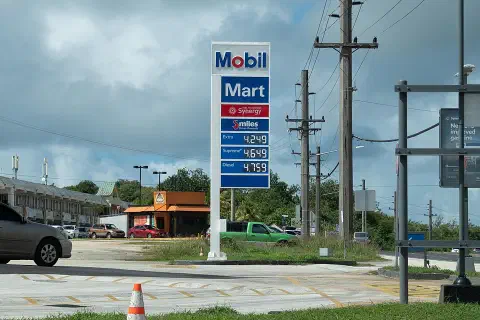
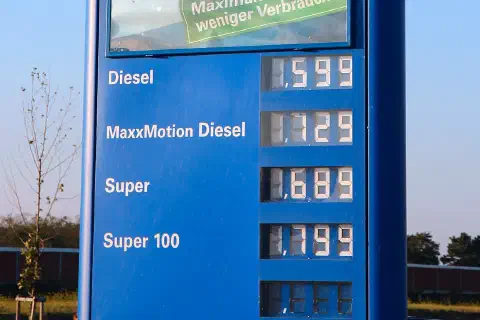
Diesel is the cost that reaches everything. Most goods sold in America travel part of their journey by lorry, and trucking firms add fuel surcharges that adjust weekly with the price of diesel, so a rise in crude reaches shippers' invoices within days. Food distributors, which move perishable goods in refrigerated vehicles over short distances many times a week, feel it more than most.
Tariffs on steel reach machinery
The steel tariff, raised to 50 per cent in June 2025, no longer stops at raw metal. Duties now apply to the steel content of a long list of finished and part-finished goods, from machinery to appliances, which means a factory buying a new production line pays more for it even if it never buys a tonne of steel directly. Domestic steelmakers have room to raise their own prices behind the tariff wall, so buyers who switch to American suppliers find only limited relief. The cost lands in capital spending budgets as well as in the cost of goods sold.
Margins look set to shrink
Consumers are starting to push back on prices, so companies can no longer pass on 100 per cent of higher wholesale costs to their customers. Some of the increase will have to come out of profits. Gross and operating margins are therefore likely to narrow when companies report third-quarter results in the coming weeks.
The producer price index offers a clue to who is absorbing the squeeze. Its trade services component measures the margins wholesalers and retailers earn on the goods they sell, and a fall in that component means distributors are swallowing cost increases instead of passing them on. Food distributors, which operate on thin margins and sell to price-sensitive grocers and restaurants, are among the most exposed to that squeeze.
Food distributors face an extra complication. Their customers include restaurants and grocers already under pressure from shoppers trading down, so the room to raise prices is narrow, and their own contracts often fix selling prices for weeks or months while fuel and packaging costs adjust at once. That timing mismatch means a rise in producer prices tends to hit distributors' quarterly margins before it reaches the grocery aisle.
Operating leverage magnifies the effect. A manufacturer with heavy fixed costs for plant, equipment and salaried staff sees operating profit fall proportionally more than gross profit when input costs outrun prices, because the fixed costs do not shrink. Chemical makers, whose plants earn most when running near full capacity, are especially exposed if weaker demand forces them to cut output at the same time. Refiners, domestic steelmakers and producers of feedstocks sit on the other side of the same numbers and earn more as those prices rise.
For the Fed, producer prices are an early warning. Several components of the index, including airfares and portfolio management fees, feed directly into the personal consumption expenditures price index, the Fed's preferred gauge of inflation, which is why economists revise their forecasts of that measure as soon as producer prices are published.
Lessons from 2008 and 2021
Two recent episodes mark the range of outcomes. In 2021 and 2022 producer prices surged, but demand was so strong that companies passed costs on and many reported record margins. In the first half of 2008, when crude climbed towards its July peak of $147 a barrel, weakening consumer demand left manufacturers and airlines unable to recover fuel costs, and margins fell sharply before the financial crisis made matters worse. The present mix of consumer resistance and energy-led costs looks more like 2008 than 2021.
Why the squeeze may be slower
The case against an immediate hit is that many companies hedge fuel and commodity costs, sign supply contracts months ahead and carry inventory bought at older prices, so higher input costs reach the income statement with a lag. Monthly producer prices are also volatile, and one month's rise can reverse. That delays the squeeze rather than preventing it, and the hedges put in place before the energy shock will roll off over the coming quarters.
The third-quarter reporting season, the purchasing managers' surveys of prices paid and the next producer price report will show how far the pressure has travelled. Input costs are rising faster than companies can raise prices. Expect third-quarter earnings from manufacturers, chemical makers and food distributors to show thinner margins, and probably some cautious guidance for the rest of the year.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.