Saudi Arabia's pipeline around the war

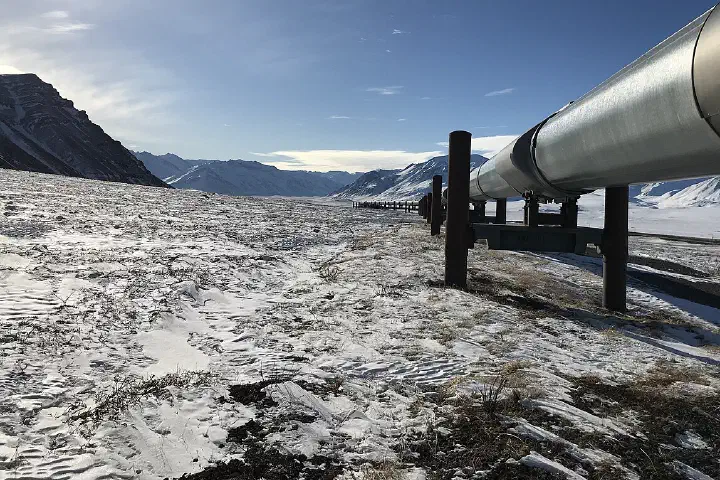
With ships still unable to move through the Strait of Hormuz, Saudi Arabia has turned to its back door. The kingdom is running its 746-mile East-West Pipeline flat out, carrying crude from its Gulf fields across the desert to the Red Sea terminals at Yanbu and keeping clear of the war zone altogether.
Built for exactly this
The pipeline was a product of an earlier war. Saudi Arabia built it in the early 1980s, as the Iran-Iraq conflict spilled into attacks on Gulf shipping, so that a closure of Hormuz would not strand all of its exports. For most of the four decades since, it has carried a fraction of its capacity, a costly insurance policy that looked like an extravagance in peacetime. Aramco raised its capacity in 2019 by converting lines that once carried natural-gas liquids, which is how it reached the level it is running at now.
Seven million barrels a day
The East-West Pipeline, known as Petroline, is the region's main insurance policy against a closed strait, with capacity of roughly seven million barrels per day. By sending Arabian Light and Super Light west, Saudi Aramco can keep supplying refiners in Europe and the Mediterranean without going anywhere near Hormuz.
Capacity on paper and exports in practice are not the same thing. Some of the crude arriving at the Red Sea coast feeds refineries at Yanbu and Jeddah rather than export terminals, and the loading berths at Yanbu were not designed to handle the kingdom's entire export programme at once. How much of the seven million barrels actually leaves by sea depends on how quickly tankers can be cycled through the port, and on how many owners are willing to charter ships into the region at all.
Domestic demand competes for the same barrels. Saudi Arabia burns large volumes of crude in its own power stations during the summer to meet air-conditioning demand, and that consumption rises just as the hot season begins. Every barrel burned at home is a barrel not exported through Yanbu, so the kingdom's export capacity through the pipeline is likely to tighten through the summer months even if the line runs at full rate.
Pricing is the other lever. Aramco sets official selling prices for each grade and region every month, and it can use them to steer its reduced exports. Raising prices for Asian buyers relative to European ones, or the reverse, determines which refiners get the scarce barrels, and it tells the market which customers the kingdom regards as its priority during the crisis.
The route beyond Yanbu
Once loaded, cargoes face a choice of two exits. Northbound tankers can travel up the Red Sea to the Suez Canal, or unload at the Egyptian end of the SUMED pipeline, which carries crude from the Gulf of Suez to the Mediterranean. Southbound tankers must pass through the Bab el-Mandeb strait, where Houthi forces in Yemen attacked merchant shipping from late 2023 and forced most large shipping lines to divert around Africa. The Red Sea is safer than the Gulf, but it is not safe, and insurers price it accordingly.
The pipeline itself is exposed too. In May 2019 drones struck two pumping stations on the East-West line, and in September of that year an attack on the Abqaiq processing plant briefly knocked out about half of Saudi output. The infrastructure that now carries the kingdom's exports runs across hundreds of miles of open desert, and it has already been shown to be within reach of anyone with drones.
Egypt is an unexpected beneficiary. The Suez Canal and the SUMED pipeline earn fees on every northbound cargo, and canal revenue fell sharply after Houthi attacks diverted shipping away from the Red Sea from late 2023. A surge of Saudi crude heading north from Yanbu would restore part of that income, provided the northern Red Sea stays out of the fighting.

The 13-million-barrel gap
For the world as a whole, the arithmetic is less comforting. In normal times twenty million barrels a day pass through Hormuz. Seven million barrels of pipeline capacity rescues barely a third of the Gulf's usual exports. Kuwait, Iraq and the United Arab Emirates have no comparable route, and their crude stays stuck behind the blockade.
The Emirates come closest. A pipeline from the Habshan fields to Fujairah, on the Gulf of Oman outside the strait, lets Abu Dhabi export part of its crude, but its capacity is a fraction of Petroline's. Iraq's southern fields around Basra, which supply most of its exports, depend entirely on the Gulf, and its northern route through Turkey handles far smaller volumes. Kuwait and Qatar have no bypass at all, which means Qatar's liquefied natural gas is trapped along with the crude.
Winners and losers inside OPEC
The closure redistributes income sharply within the Gulf. Saudi Arabia sells millions of barrels a day at crisis prices, so its revenue may hold up or even rise despite lower volumes. Its neighbours without a bypass lose almost all of their export income while the strait is shut, and their budgets depend heavily on it. European refiners that can buy Saudi crude through the Red Sea gain relative to Asian refiners, which traditionally take the bulk of Gulf exports and must now compete for Atlantic Basin cargoes. Aramco's pricing to different regions will show whom it chooses to favour.
The limits of a back door
The strongest counterargument is that Petroline, combined with strategic stocks, higher output elsewhere and lower demand, may be enough to prevent a true shortage if the closure is brief. That view underestimates the time it takes for output elsewhere to respond, and it assumes the pipeline and the Red Sea route stay secure. Neither assumption can be taken for granted in a regional war.
The signals to watch are tanker loadings at Yanbu, transits through the Suez Canal and flows through the SUMED pipeline, security in the Bab el-Mandeb, and the official selling prices Aramco sets for Asian and European buyers each month. Aramco's western customers will probably keep getting their oil. Everyone else is short thirteen million barrels a day, and no pipeline in the region can make that up while the strait stays shut.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.