Tariffs haven't dented Big Tech's AI spending

Alphabet has confirmed that its capital spending will run above $75 billion a year, and Microsoft and Meta have repeated their own large plans for AI infrastructure. Industrial manufacturers, retail chains and carmakers have been cutting capital budgets as the trade war escalates. The biggest technology companies have carried on as though it were not happening.
Alphabet's reaffirmation came with its first-quarter results on April 24th, which beat expectations on the strength of search advertising and a fast-growing cloud business. Its shares rose. That contrasts with the companies that have withdrawn guidance this month, and with the anxious tone of earnings calls in consumer goods, transport and manufacturing. The market is treating AI spending as a commitment made years in advance, and so far the companies making it have not blinked.
How the spending got this big
The surge began with the launch of ChatGPT at the end of 2022, which convinced the largest technology companies that generative AI would reshape search, software and cloud computing. Training ever-larger models and serving them to hundreds of millions of users requires enormous numbers of specialised chips, mostly designed by Nvidia and made by TSMC in Taiwan, along with new data centres and the electricity to run them. In January, Microsoft said it would spend about $80 billion on AI-capable data centres in its current fiscal year, and Meta guided to $60 billion to $65 billion for 2025. OpenAI, SoftBank and Oracle announced a joint venture, Stargate, with plans for up to $500 billion of American AI infrastructure.
That appetite survived its first serious test in late January, when the Chinese start-up DeepSeek released a model that it said had been trained cheaply. Nvidia's shares plunged, and investors asked whether the spending was excessive. The companies answered by raising or reaffirming their budgets, arguing that cheaper models would increase demand for AI rather than reduce the need for computing power.
Tariffs are a rounding error
Hyperscalers' spending barely responds to prices or policy, because they see AI as a race for control of the next computing platform. Inside Big Tech boardrooms, the cost of under-investing in compute, whether that means losing the lead in foundation models or losing developers to a rival, looks far larger than a 10 or 25 per cent tariff on imported networking gear or server chassis.
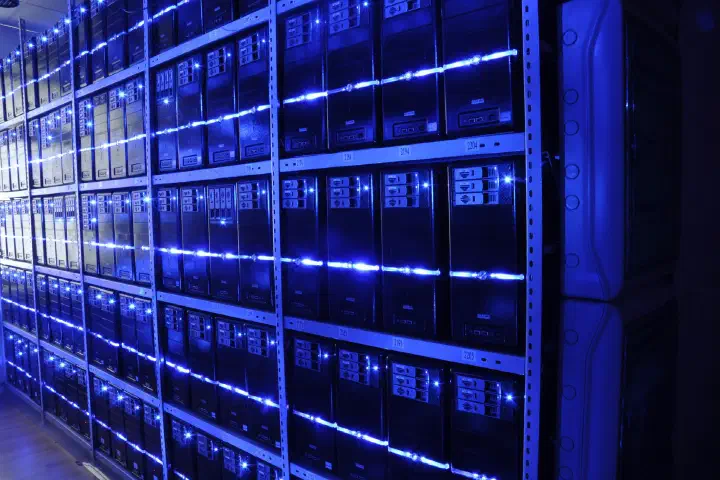
The tariff exposure is also smaller than it looks. Semiconductors were exempted from the reciprocal tariffs announced on April 2nd, and a later exemption covered computers and many electronic components. Much server assembly for the American market takes place in Mexico, and goods that qualify under the USMCA escape the new levies. The biggest cost in an AI data centre, the accelerator chips, is therefore largely untouched for now. What is taxed, such as steel for buildings, electrical equipment and some networking hardware, is a small fraction of the total bill.
Cash buys the servers
Manufacturers work on thin gross margins and borrow heavily to fund working capital. The mega-cap technology firms have huge balance sheets and enormous cash flows from software. That money lets them pay border surcharges on hardware without much pain, and it also pushes smaller companies to the back of the queue for compute.
The queue works through several channels. Nvidia allocates scarce supply of its newest chips, and its largest customers, who place orders years ahead, get priority. Cloud providers reserve much of their capacity for their own models and their biggest clients. Smaller AI start-ups, universities and ordinary companies that want to rent computing power pay higher prices or wait longer. Tariffs on the remaining hardware add a further cost that a firm with software margins can absorb and a firm without them cannot.
Where policy does bite
Trade policy is not irrelevant to the sector. Earlier this month Washington required licences for sales of Nvidia's H20 chip, designed for the Chinese market, and Nvidia said it expected a charge of about $5.5 billion as a result. An investigation into whether to impose tariffs on semiconductors on national-security grounds is under way. If chips themselves become subject to heavy duties, the calculation for data-centre builders would change far more than it has so far. Nvidia has also announced plans to build AI supercomputers in America with its manufacturing partners, partly to reduce that exposure.

The bigger constraints may be physical rather than fiscal. Data centres need large amounts of electricity, and utilities in several regions are struggling to connect them fast enough. Transformers, switchgear and turbines are in short supply, and some of them are imported. Those bottlenecks could slow the spending more than any tariff.
The bear case on capex
The strongest counterargument is that the spending itself is the risk. Revenue from AI products, while growing, remains small relative to the capital being deployed, and depreciation on servers that may become obsolete within a few years will weigh on margins. There were reports earlier this year that Microsoft had walked away from some data-centre leases, which sceptics read as a sign of over-building. If a recession cuts advertising and cloud budgets, investors may lose patience with capital spending that does not pay back quickly.
Watch the results from Microsoft and Meta next week, the next guidance from Amazon, the outcome of the semiconductor tariff investigation and Nvidia's results in May. Any trimming of capital plans would signal that the race is being run with more caution, which would help margins but hurt the suppliers that depend on it.
Winners and losers from the race
The winners are chip designers and manufacturers, makers of power and cooling equipment, builders of data centres and the utilities that serve them. The largest cloud providers gain a lasting advantage over smaller rivals that cannot match their spending. The losers are companies that need computing power but cannot buy it on the same terms, and, in a slowing economy, shareholders who might prefer the cash as dividends or buybacks.
For now, the AI race is running well clear of trade policy, paid for by software profits that tariffs barely touch, and smaller companies that need servers will probably find them scarcer and dearer. Unless chips themselves are hit by tariffs, expect the biggest spenders to hold their budgets through the rest of the year, while start-ups and mid-sized firms pay more and wait longer for the same capacity.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.