Tariffs still aren't showing up in prices
May's consumer price index put headline inflation at 2.4 per cent year-on-year, and once again the tariff-driven surge that many had expected failed to appear. Economists who study supply chains are not surprised. Pass-through happens in stages, and accounting cycles set the timetable.
The detail was just as calm as the headline. Core prices, which exclude food and energy, rose only a tenth of a percentage point in the month, the fourth soft reading in a row, and the annual core rate held at 2.8 per cent. Airfares and new-car prices fell. Shelter, the largest item in the index, kept cooling slowly. For a Federal Reserve that meets next week, the figures offered no reason to panic and no reason to cut.
Where it already shows
The tariffs are not invisible. Prices of some heavily imported goods, household appliances among them, rose in May, and the categories most exposed to Chinese factories have stopped falling after years of steady declines. Those movements are small against a basket dominated by rent, health care and other services that tariffs barely touch. A rise in the price of toasters is hard to see in an index where housing carries a weight of about a third.
The money is visible elsewhere. Customs receipts have climbed to record monthly levels this spring, which means someone is paying the duty now. The only question is how long it takes for that bill to move from importers' accounts to shoppers' receipts.
Old stock, old prices
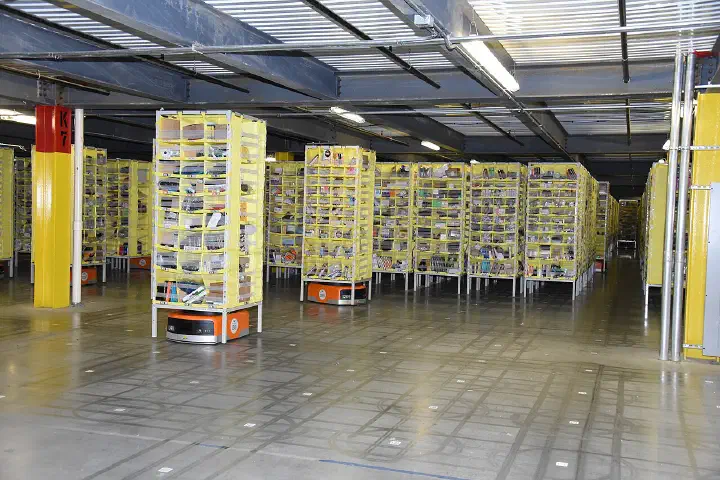
Under first-in, first-out (FIFO) inventory accounting, companies expense their oldest goods first. Much of what they sell today entered warehouses months ago at pre-tariff landed costs. Importers rushed goods in during the first quarter to beat the duties, and that buffer is only now running out. Multinational brands also tend to revise wholesale price lists twice a year, so border taxes paid in April and May will probably not reach shop shelves until the autumn catalogue resets.
Accounting sets the clock
The accounting rules shape the timing in a specific way. Customs duty counts as part of the cost of inventory, so a tariff paid at the port sits on the balance sheet until the goods are sold, and only then does it reach the cost of goods sold. A retailer that turns its stock over every three months will feel a tariff in its margins about a quarter after paying it. A furniture or appliance seller that holds goods longer will feel it later still.
Companies that use last-in, first-out accounting, more common among some American wholesalers and industrial distributors, see the newest and dearest costs sooner, and they have a stronger incentive to raise prices early. The mix of accounting methods across the economy is one reason pass-through arrives as a slow drip rather than a single jump. It also means that the most tariff-sensitive prices, in goods with short shelf lives and fast turnover, should move first.
Wholesale costs already up
Reading lagging consumer price data as proof that tariffs do not cause inflation is a serious mistake. Surveys of freight forwarders, customs brokers and industrial purchasing managers show wholesale landed costs rising sharply in every major category of imported goods.
The official figures point the same way. The import price index is measured before duty is added, so if foreign suppliers were absorbing the tariffs by cutting their prices, it would be falling steeply. It has not fallen much. The prices-paid gauge in the manufacturers' survey of the Institute for Supply Management has been running near its highest level since 2022. Both suggest the duty is being paid in full at the border and held, for now, in the margins of American importers and retailers.
Britain's slow burn after 2016
Britain offers a useful guide to timing. After the Brexit referendum in June 2016, sterling fell sharply, raising the cost of imports in much the same way a broad tariff would. Consumer price inflation barely moved for the rest of that year. It then climbed steadily through 2017 and peaked in the autumn, more than a year after the shock, as importers' hedges and old stock ran out and new price lists took effect. The lesson for America is that a quiet first few months says little about the size of the eventual effect.
The 2018 and 2019 tariffs on China show the same pattern in American data. Studies found that import prices rose by close to the full amount of the duties, while the effect on shop prices came later and was spread over many months. The shock this year is much larger and broader, so even a partial and delayed pass-through would add noticeably to goods inflation.
What would change the call
The strongest case against the forecast is that demand is softening. Shoppers who resist higher prices could force retailers and brands to absorb more of the duty for longer, and the truce with China has cut the heaviest rates. In that case the cost would show up in profits and eventually in hiring rather than in the price index. That would be a different kind of damage, not an absence of it.
The indicators to watch are core goods prices in the June and July reports, the pricing guidance retailers give for the back-to-school season, and the Fed's new projections next week, which will show how much tariff inflation its officials expect. The benign May figure will not last. Once the cheap inventory has been sold, probably by the autumn, double-digit border duties will start feeding into consumer prices, and they will be hard to miss. Core goods are likely to be the first place the shift appears, and by the time it does, the Fed will have spent another two meetings waiting for evidence that was sitting in the customs receipts all along.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.