America and China call a truce

Washington and Beijing surprised markets with a 90-day trade truce that rolls back their triple-digit tariffs to an interim level. America will charge 30 per cent on Chinese goods and China 10 per cent on American ones. Shares and government bonds around the world rallied at once in relief.
What was actually agreed
The deal came out of a weekend of talks in Geneva, and it is narrower than the market's mood suggests. America's 30 per cent is made up of a 10 per cent reciprocal duty, the same baseline charged on most countries, plus a separate 20 per cent levy tied to Washington's complaints about fentanyl. That second part was not reduced. For many products the new rate also sits on top of duties left over from the first trade war, which remain in force.
Those older duties are not trivial. The tariffs imposed in 2018 and 2019 run at up to 25 per cent on large swathes of machinery, electronics components and industrial goods, so some Chinese products will still pay well over 50 per cent in total. Both sides also agreed to keep talking through a standing channel, led on the American side by the Treasury secretary, Scott Bessent, and on the Chinese side by the vice-premier, He Lifeng. China said it would suspend or remove the non-tariff countermeasures it had taken since early April.
Neither side could hold out
The truce shows that tariffs of 145 per cent, high enough to act as an embargo, could not be kept up. Both governments saw that halting trade altogether was doing serious harm. American importers were running short of parts, and factories in China's export hubs were standing idle. The 90-day pause gives supply chains time to clear the cargo stuck in customs and to regain some basic predictability.
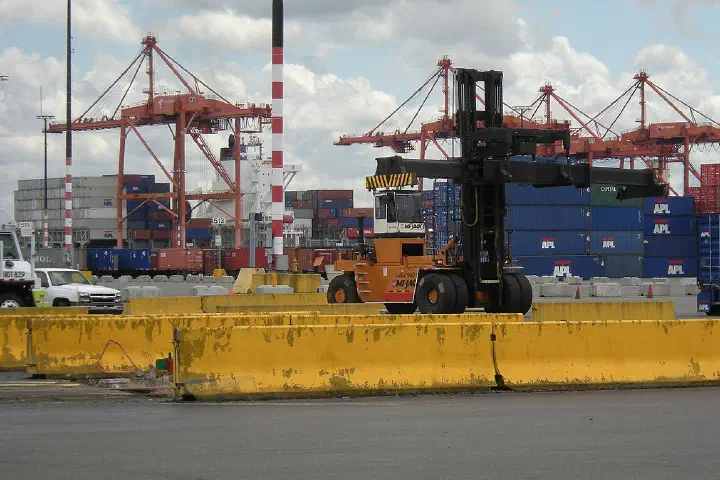
The pressure showed first at sea. Container bookings from China to America dropped sharply in April as importers cancelled or postponed orders rather than pay the duty, and ports on America's west coast were bracing for a thin May. China's own export figures for April held up better than feared only because shipments to South-East Asia and other markets rose while those to America fell.
Duty paid at the dock
The mechanics explain why the cut matters so quickly. American tariffs are paid in cash by the importer of record when goods clear customs, long before the goods are sold. At 145 per cent, a retailer bringing in $1m of Chinese stock had to find $1.45m for the government on top of paying the supplier, a sum few small firms could finance. Many chose to leave goods in bonded warehouses, where duty is not owed until the goods are withdrawn, or to keep them on the factory floor in China.
At 30 per cent, that same shipment needs $300,000 of duty. Still painful, but it is a cost that can be financed and partly passed on, which is why goods held back in April can now move. The administration also cut the duty on low-value parcels sent directly to American consumers, which matters to the Chinese online retailers that have built businesses on shipping small packages across the Pacific.
The last 90-day truce
There is an uncomfortable precedent. In December 2018, at a dinner during the G20 summit in Buenos Aires, the two presidents agreed a 90-day truce to allow talks. Those talks broke down the following May, when Washington raised its tariffs on a large slice of Chinese imports, and a limited first-phase deal was not signed until January 2020. The lesson is that a pause buys time for negotiation without guaranteeing one, and that tariffs set during the fight tend to outlast it.
Who gains from the window
The first effect will be a rush. Retailers ordering for the back-to-school season and Christmas will try to ship as much as possible before the pause runs out in August, which should lift freight rates across the Pacific and fill warehouses again. American importers of toys, electronics and furniture, which lean heavily on Chinese factories, gain the most. Rival suppliers in South-East Asia and Mexico lose part of the advantage they had enjoyed while Chinese goods were shut out, though Chinese goods still pay three times the 10 per cent charged on most other countries.
The strongest case against caution is that the direction of travel has changed. Both sides have shown they will retreat when the damage becomes visible, and a further cut, perhaps to the fentanyl levy, is possible if talks go well. That is a reasonable hope. It is not a planning assumption, because the 20 per cent part of the tariff depends on a political judgement in Washington that Chinese exporters cannot influence.
Rare earths and other levers
China kept some of its strongest cards. In early April it added seven rare-earth elements, used in magnets for cars, wind turbines and weapons, to a list of exports that need a licence, and licences have been slow to arrive. Whether the promise to suspend countermeasures covers those controls is not yet clear. American carmakers and defence contractors will judge the truce by whether magnet shipments resume, more than by the headline tariff.
The rollback also changes the calculus at the Federal Reserve. Lower duties on the largest source of American consumer imports reduce the inflation shock the Fed had been bracing for, and they reduce the risk of a sharp slowdown. Traders responded by scaling back bets on rate cuts this year, a sign that markets think the Fed has less reason to hurry.
A tense peace at 30 per cent
The rollback avoids an immediate breakdown, but a baseline tariff of 30 per cent is still a heavy and lasting drag on trade between the two countries. It is three times the level of the original duties imposed in 2018. The signals to watch are progress on the fentanyl dispute, any easing of China's curbs on exports of rare earths and other materials, and whether the 90-day deadline is extended without fuss or with a fresh threat. Even after the cut, America's average tariff on imports stays higher than at any time since the 1930s. Exhaustion, not goodwill, produced this truce, and companies trading across the Pacific should plan on paying at least 30 per cent for the foreseeable future, whatever happens when the 90 days run out.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.