How much will oil push up prices?

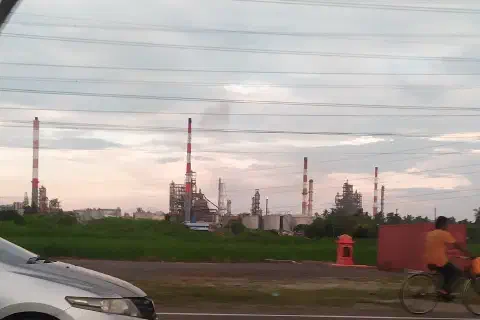
Brent crude is trading well above $100 a barrel for the first time since August 2022, and central bank economists are rushing to redo their estimates of how much will feed through into wider inflation. Oil at a hundred dollars hits differently in an economy where labour markets are tight than it did in earlier decades.
Why the regime matters
The research on this question is fairly settled about the past. In the 1970s, oil shocks fed quickly into wages because many pay contracts were indexed to inflation, central banks had little credibility, and economies used far more oil for each unit of output. By the 2000s the same percentage rise in crude produced much smaller effects on inflation and output, a finding associated with work by Olivier Blanchard and Jordi Galí. Their explanation was that labour markets had become more flexible, monetary policy more credible and production less oil-intensive. The uncomfortable question now is whether the first two conditions still hold after the inflation of 2021 and 2022.
From the pump to the grocery bill
The first effect is mechanical. Petrol and diesel prices at the pump jump within seventy-two hours and push up headline consumer prices. The bigger risk comes after that, as airlines add fuel surcharges to fares, diesel surcharges raise the cost of getting food to shops, and dearer chemical feedstocks lift factory costs. With headline inflation already close to three per cent, rising fuel bills could quickly change what workers expect in pay.
The arithmetic of the first round is simple. A barrel holds 42 gallons, so each $10 rise in crude adds roughly 24 cents to the cost of a gallon of petrol once refiners and retailers pass it on, before any change in refining margins. Motor fuel makes up only a few per cent of the consumer price basket, but it is the most volatile item in it, and it is also the price households notice most often. That visibility is what links the first round to the second, because people form their inflation expectations partly from what they pay at the pump.
Headline inflation near three per cent means the shock arrives before the last one has fully cleared. The Fed targets 2 per cent on the price index for personal consumption expenditures and pays most attention to its core measure, which excludes food and energy. An oil shock lifts the headline figure at once, but it reaches the core only through transport costs, airfares and the prices of goods made with petroleum inputs. The longer headline inflation stays above core, the greater the risk that households stop distinguishing between the two.
The Gulf war of 1990 is the closest precedent for a short shock. Crude roughly doubled within months of Iraq's invasion of Kuwait, headline inflation rose sharply and then fell back once prices reversed early in 1991, because wages did not follow. The American economy was already weakening and slid into recession, which did more to contain inflation than any decision by the Fed.

The second round
Second-round effects work through three channels. Businesses that use fuel as an input raise their own prices, so transport, food and airfares follow crude with a lag of weeks or months. Workers who see their real incomes squeezed ask for higher pay, and in a tight labour market they are more likely to get it. Finally, if households and firms come to expect higher inflation, they build it into contracts and price-setting, and it becomes self-sustaining. Central banks can tolerate the first channel. It is the second and third that force them to act.
Companies will pass it on
Economists' models show that when inflation is low, companies tend to absorb energy spikes in their margins. After three years in which they have had strong pricing power, they are more likely to pass the extra cost straight to customers.
The experience of 2021 and 2022 changed corporate behaviour. When costs rose across the board and every competitor raised prices together, companies found that customers accepted increases they would once have resisted, and profit margins in many industries widened rather than narrowed. Managers who learned that lesson are unlikely to wait long before repricing again, particularly in industries where a few large firms set prices and each can reasonably expect the others to follow.
What argues for restraint
The case against a large second-round effect is real. Advanced economies use far less oil per dollar of output than they did in the 1970s, so a given rise in crude takes a smaller bite out of incomes. A sharp rise in fuel costs also acts as a tax on households, which cuts spending on other things, and weaker demand limits how far firms can push prices elsewhere. Long-term inflation expectations, as measured in bond markets, stayed anchored through much of the last surge. If they do so again, central banks can argue that the shock will pass through the price level once and fade.
Precedent offers a warning about acting too quickly, too. The European Central Bank raised rates in July 2008 as oil hit a record, weeks before the financial crisis deepened, and raised them twice more in 2011 in response to energy-driven inflation, only to reverse course within months as the euro area slid back into recession. Both episodes are cited inside central banks as reasons to look through supply shocks unless there is clear evidence that they are spreading.
Winners, losers and the data to watch
Oil producers, refiners with access to cheaper crude and firms with pricing power stand to gain from the shift. Households on low incomes, who spend a larger share of their budgets on fuel and food, lose most, along with companies in competitive markets that cannot pass costs on and borrowers hoping for lower interest rates. The indicators that will settle the argument are monthly core inflation, wage settlements and the employment cost index, surveys of household inflation expectations, and the five-year, five-year forward inflation rate in bond markets. Oil above $100 will push up costs across the economy. Central banks will probably have to shelve plans for further rate cuts for most of the year.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.