The Fed slows its balance-sheet shrinking
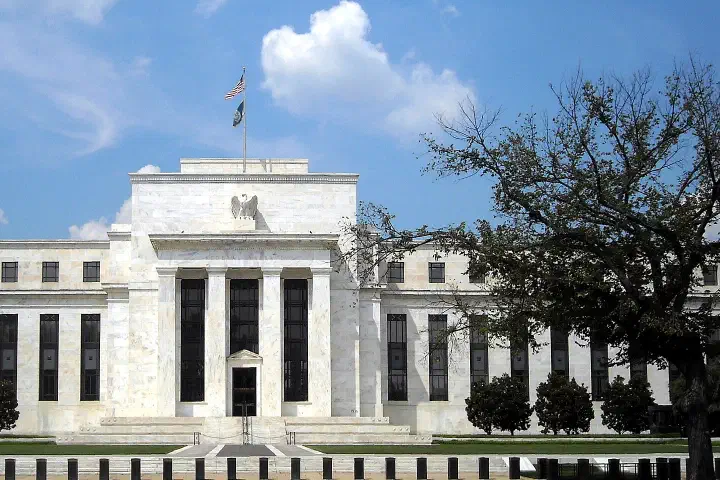
The Federal Reserve said at its May meeting that it will slow its quantitative tightening (QT) programme from June. The monthly cap on Treasuries allowed to mature without reinvestment falls from $60 billion to $25 billion, a sizeable change to the machinery of monetary policy.
Two years of runoff
QT began in June 2022 and reached full speed that September, with caps of $60 billion a month for Treasuries and $35 billion for mortgage-backed securities. Since then the balance sheet has shrunk from a peak of about $9 trillion to below $7.5 trillion. The mortgage cap stays at $35 billion under the new plan, but because prepayments are slow at today's mortgage rates, actual runoff of those securities has been running well below it. Any principal above the cap will now be reinvested in Treasuries.
The decision had been trailed. The minutes of the March meeting showed that most officials favoured slowing the pace fairly soon, and the only surprise on 1 May was that the new Treasury cap was lower than the $30 billion many dealers had expected. The change leaves the policy rate untouched at 5.25 to 5.50 per cent, and the Fed has been at pains to separate the two decisions.
Protecting bank reserves
Jerome Powell wants to avoid a repeat of the September 2019 seizure in the repo market. The Fed's overnight reverse repo facility is draining fast, and once it is empty, full-speed QT would pull cash straight out of bank reserves. Slowing the runoff lets the Fed keep shrinking its balance sheet for longer while cutting the risk of a scramble for funding in wholesale markets.
The mechanism is worth spelling out. When a Treasury security held by the Fed matures and is not replaced, the Treasury must borrow the money from private investors instead. Those investors pay with cash that comes either from the reverse repo facility, where money-market funds park surplus funds at the Fed, or from bank deposits, which reduce reserves. For most of the past two years the reverse repo facility took the strain, falling from more than $2 trillion at its peak in late 2022 to under $500 billion now. As it approaches its floor, each further dollar of runoff comes out of reserves.
What happened in 2019
The last time the Fed shrank its balance sheet, it misjudged how many reserves the banking system needed. It had already slowed the runoff in May 2019 and ended it that August, yet in mid-September a corporate tax date and a large Treasury settlement drained cash at the same moment. Overnight repo rates spiked to around 10 per cent intraday, far above the Fed's target range, and the central bank had to inject liquidity through emergency repo operations and then begin buying Treasury bills.
That episode showed that demand for reserves is not stable. Banks hold more than the regulatory minimum for internal liquidity reasons, and the level at which they start to compete for cash is hard to identify in advance. By slowing the runoff while reserves are still plentiful, the Fed is giving itself time to watch for early signs of strain, rather than discovering the threshold the hard way.

The Fed also has better tools than it did five years ago. The standing repo facility, created in 2021, lets eligible dealers and banks borrow against Treasuries at a set rate, which should cap spikes in overnight funding. Its existence makes a repeat of 2019 less likely, though the facility has been barely used and some banks still worry that tapping it signals weakness.
Who notices the change
The direct effect on long-term yields is modest. Slowing runoff by $35 billion a month means the Treasury needs to sell somewhat less debt to the public, which removes a little pressure from the market at the margin. Banks gain the most, as reserves decline more slowly and the risk of funding strains at quarter-ends recedes. Money-market funds may see repo rates stay closer to the lower end of the Fed's range for longer.
The Treasury also benefits. Slower Fed runoff reduces the amount it must raise from private buyers, which makes it easier to keep coupon auction sizes steady, as it promised again at its own refunding announcement on 1 May.
The case against easing off
The strongest objection is one of timing. Inflation has surprised on the upside for three months, and slowing QT while the policy rate stays put looks to some critics like an easing of financial conditions by the back door. If the Fed wants tight policy, the argument goes, it should use every lever. There is also a risk that markets read the move as a first step towards rate cuts, which the committee is plainly not ready to make.
The Fed's answer, which is persuasive, is that QT is a tool for managing the size of the balance sheet, not for fine-tuning the economy. The difference between runoff of $60 billion and $25 billion a month is small next to the effect of the policy rate itself. The trade-off is between a slightly slower glide path and a lower risk of a disorderly funding event that would force the Fed to reverse course abruptly, as it did in 2019.
Signals to watch
The indicators that matter are in the money markets. A rise in the secured overnight financing rate relative to the interest the Fed pays on reserves, persistent pressure at month-ends and quarter-ends, and heavier use of the standing repo facility would all suggest reserves are getting scarce. The level of the reverse repo facility, and the size of the Treasury's cash balance at the Fed, will show how quickly the remaining buffer is being used up. Officials have said they intend to stop runoff when reserves are somewhat above the level they judge to be ample.
The Fed is being sensible. By easing off now, before runoff starts eating into bank reserves, it should spare money markets a repeat of 2019, and it can go on shrinking the balance sheet with less risk of an accident. Expect runoff to continue at the slower pace well into next year, with little visible disruption to funding markets along the way.
Write to Arnav Goel at contact@thelombardreview.com
The Sunday Edition, in your inbox
India's economy, markets and money every Sunday, plus our analysis twice a week. Free.
Unsubscribe any time. See our Privacy Notice.